Reflections & analysis about innovation, technology, startups, investing, healthcare, and more .... with a focus on Minnesota, Land of 10,000 Lakes. Blogging continuously since 2005.

Category: Entrepreneurs (Page 1 of 2)

How Minnesota Is Making Its Mark In the Fintech Industry

We Ask Several Notable State Names to Weigh In

(Note: This post first appeared in Next In The North.)

Minnesota has been a center for financial services for decades. You know the names – big banks, wealth management firms, capital markets players, giant insurance companies – most still with a significant presence here. But where are we today in our state now that new financial technologies are flooding into the daily lives of consumers and businesses everywhere?

We collectively call this new industry “fintech,” but it’s made up of many sectors – banking, payments, lending, wealth management, insurtech, and more. Minnesota has several growing fintech firms already making a big mark, and several more startups are breaking out.

“The growth of fintech is an interesting pattern of companies using financial technology to solve very practical problems for workers, families, small businesses, and industries that historically have not been well served by financial products or modern software,” said Ryan Weber, cofounder of Great North Ventures. He cited areas such as faster access to wages, better insurance access, financial tools embedded into workforce platforms, products for small-business money management, and other applications where better financial infrastructure creates both economic value and better customer outcomes.

A Minnesota venture capital firm that’s a well-known leader in fintech investing is Rally Ventures. “Fintech and, more broadly, regulated financial industries, form the basis of the Rally Ventures AI+ thesis — previously SaaS+,” said Justin Kaufenberg, managing director. “We’ve been focused on this theme since inception. When your core economic engine is the credit card payment, the insurance policy, the background screen, the loan product, the payroll product, or the funds distribution service, it means you can irrationally invest the underlying platform. The customer feels fortunate to receive such a robust platform, at such an affordable price. We disrupt the incumbent financial institutions, allowing us to delight the customer. Done correctly, it is nearly impossible for a traditional software/Ai company to compete.”

A Fertile Training Ground

John Stavig is Managing Director of the Gary S. Holmes Center for Entrepreneurship at the U of MN Carlson School of Management. “I don’t believe we’ve realized our full potential, given the innovation capacity of the local banks and insurance companies. This is one of the reasons Plug and Play has brought their accelerator programming to the Twin Cities, through the support of Allianz, Bremer Bank, and others.”

I asked him what Minnesota fintech companies especially stand out for him. “Sezzle is a tremendous local success story with a market cap approaching $4 billion. What started out as an early BNPL company has continuously innovated to develop lasting relationships with younger consumers by helping them manage convenient digital credit services,” Stavig said. “Branch is another innovative fintech that started with workforce scheduling and evolved into a financial services provider for hourly employees.”

Stavig’s involvement with the MN Cup startup competition gives him a special perspective. “In addition to Sezzle’s past participation, we’ve had several payment processing companies, such as Mozrt, participate in in recent years.” Do startups have an edge in fintech specifically? “They seem to be able to more quickly pursue niche opportunities that can turn into attractive acquisition candidates for slower-moving corporations. Given their legacy platforms and customer base, the big financial corporations seem better positioned to acquire, rather than build, new technology platforms.”

Stavig sees Carlson School students’ fintech interest firsthand. “I just came from a class where students were discussing a number of challenges with financial literacy and personal credit management. It’s definitely an area where they see opportunities for improvement.”

He called out another MN Cup startup from this year’s Impact Division: Duome. “They’re very early, but ambitiously taking on the big issue of housing affordability.”

Our universities in Minnesota have produced several successful fintech founders, certainly including the two who launched the aforementioned Sezzle, Charlie Youakim and Paul Paradis, both U of MN Carlson School MBAs; another founder, Brandon Dols, a St. Cloud State grad, founded Figg, which was acquired by JPMorgan.

It’s also true that many Minnesota university grads, now employees at local fintech startups, cut their teeth in the financial services business here by having previously worked at our locally based big banks or insurance companies.

Fintech startups can pop up anywhere, including outside the Twin Cities metro area. Susan Sorensen Langer studied at the U of MN Carlson School and began her career at USBank. She went on to become founder and CEO of Spave, which is based in Red Wing, Minnesota. Spave is a social giving app that empowers individuals, employers, and nonprofit partners to automate saving and giving through everyday spending.

Myles Shaver is a Professor and Curtis L Carlson Chair in Corporate Strategy at the U of MN Carlson School. “Our region has the ingredients to be a player in fintech,” he said. “The banking systems that grew into Well Fargo, from Norwest Bank, and US Bank both originated here, as did other financial institutions such as IDS and St. Paul Companies. Because we’re a business center where finance is important, combined with our history in software and computing, that gives Minnesota the talent base to help found and grow fintech.”

He too noted that Carlson School students have clear interest in new financial technologies. “It does make its way into our classes. The success of fintech often comes from relaxing frictions or capitalizing on blind spots in the current banking system. So, understanding those fundamentals will always be key and a part of our curriculum.”

Shaver said he’s sure all major financial institutions are experimenting with fintech to some degree. “The outside view that startups bring is often key in something like this and can lead the banks to augment their internal development with acquisitions,” he added.

Fintech Founders Speak Out

I sought comment for this article from three Minnesota entrepreneurs who have achieved notable success:

• Brock Noland cofounded pH Data in 2014 to build intelligent systems for enterprises, to help form the foundations AI depends on. It has grown to roughly 930 employees worldwide after raising just $2.5 million in disclosed venture funding, prior to a 2024 investment/acquisition by private-equity firm Gryphon Investors. In 2022, Noland cofounded Vertical Insure to help industry-specific, vertical SaaS companies increase profits through embedded insurance. It was just named to FinTech Global’s 2026 InsurTech100.

What’s Noland’s take on the current state of fintech in Minnesota? “I think we’re seeing a real renaissance of fintech in Minnesota,” he said. “I use a pretty broad definition of fintech that includes vertical software companies that monetize through fintech, along with pure-play fintechs like Vertical Insure. I think we have some of the best investors in this space in the country, and there’s a growing group of founders building fintech businesses here.” Has Minnesota been a good place to be? “We’ve attracted great people and raised capital from great investors. Minnesota has been a very good place for us to build.”

Who are some people in fintech here in Minnesota that he admires? “I think what Justin Kaufenberg and Jeff Hinck are doing through ‘Rally Built’ is really interesting. They’re aggressively founding and supporting new fintech businesses here in Minnesota, which I think is great for the ecosystem.”

I also asked Noland what trends in fintech he’s finding most interesting right now. “In my broader definition of fintech, I include software companies that monetize through financial products. Traditionally, that has mostly meant payments, either taking cards or providing cards, and relatively few companies have succeeded outside of that,” he said. “But that’s changing. In our business, we’re seeing software companies generate substantial margin by embedding insurance, lending, and other financial products directly into their platforms. The key is doing it in a way that makes sense for the customer and the transaction. I think it took the market a while to figure out how to do that successfully, but it’s definitely real now.”

Noland also had thoughts about raising money in Minnesota. “I think it’s a great time to raise capital for fintech companies here, and it’s gotten easier as the ecosystem has matured. Local investors are very savvy about fintech and there are more people here who understand these business models and what it takes to build them.”

Noland noted that most of Vertical Insure’s early funding came from local investors, including Rally Ventures, Groove Capital, Dundee, and local angels. “Greenlight Re was our primary investor outside of Minnesota and is also a strategic investor,” he said. “More recently, we brought in Updata Partners as we entered our next stage of growth.”

• Cale Johnston founded ClickSWITCH in 2013 to help banks simplify the process of bringing new account holders onboard quickly and efficiently. It was acquired in 2021 by Q2 Holdings for $65 million. In mid 2025, Johnston founded Onsetto as a commercial banking operating platform, which offers several relationship-building benefits for banks with business customers. including an offering called “SwitchAssist.” In just a year, Onsetto has raised $11 million. “Last year at this time, we had zero customers,” Johnston said. ”We now have 50 under contract, and 30 of them are live.”

What does he like about being in Minnesota? “You can run a leaner, more efficient company here. You can retain more equity as a founder. Dilution on the coasts makes that harder, not to speak of the high cost of labor there.”

Johnston said Onsetto has been targeting smaller community banks, especially those focused on small business. His experience with large banks in the past is that it can take up to two years to do a deal. “Fostering relationships over time has to be the focus there.” (At his previous startup, ClickSWITCH, Citi Bank was a customer.) He said community banks move faster, and that “big banks tend to want to build versus buy.” Locally, he named Associated Banks, Tradition Capital, Bridgewater Bank, and Bell Bank as being approachable and open to new innovations. Associated has identified Minneapolis as a growth market, and is now the ninth largest bank by deposits in the Twin Cities.

What challenges does a new fintech company face? Johnston named two: “Can you sell? And can you get them live?” With Onsetto, he said, “We’re there.”

• Michael Noble cofounded Apruve in 2013 to develop a cloud-based platform to automate business-to-business (B2B) credit, invoicing, and accounts receivable management. Its technology enabled manufacturers, distributors, and other B2B suppliers to offer customers flexible payment terms without having to manage credit risk or collections themselves. Apruve raised approximately $8.25 million in VC funding and, in December 2022, announced it was being acquired by TreviPay for an undisclosed amount. TreviPay operates a global B2B payments and invoicing network and, at the time, was processing approximately $7 billion in annual transactions across 32 countries.

I asked Noble if there was any advantage in being based in MN when he was building Apruve. “We found talented people for less, and it was less competitive to keep them around,” he said. “We never did consider moving. Being in the middle of the country is convenient for getting to both coasts.”

What about raising money as a fintech startup? “It’s always hard,” Noble said. “I like the narrowness of fintech as there are only certain investors or funds that focus there. Minneapolis is a decent banking community, so I think there is always optimism for new innovations in and around moving money.”

Noble said 100% of the money Apruve raised came from out of state, except for “a few early angels.” What did Noble say about his successful exit of Apruve to TreviPay? “It was a good exit to a company that really treated our employees well and had a great culture, which is something you don’t often hear.”

No article on Minnesota fintech would be complete without also including Minneapolis-based Branch. Atif Siddiqi founded the company in 2015 in California, then moved it to Minnesota after participating in the inaugural Techstars + Target retail accelerator program in 2016. The company’s original product was a mobile B2B scheduling and messaging app to allow retail and hospitality workers to digitize their work calendars and coordinate shift swaps. But working with hourly and gig workers, Branch learned that scheduling was only part of the problem. Shift workers faced financial stress and irregular income due to traditional bi-weekly pay cycles. So, in 2018, it pivoted. Partnering with Mastercard and Evolve Bank & Trust, it added “earned wage access” by making a fee-free debit card part of the app. It has since partnered with major backend networks like Stripe. All told, Branch has raised $133 million to date, including from Minnesota-based funds. It’s grown to more than 290 employees and has seen more than $28 billion in instant payouts issued to workers via its Branch Cards.

Influence Well Beyond Our State Borders

The impact of Minnesotans in fintech includes much more than companies headquartered here. Technologists with Minnesota roots who went on to play major roles at significant new financial services companies nationally include Jeremy Allaire, founder and CEO of crypto stablecoin leader Circle; Alex Cram, Director of Software Engineering at Bill.com; and Dan Titcomb, founder of Provide. There are doubtless other Minnesota ex-pats that would illustrate the influence our local ecosystem has on the larger fintech industry, certainly more than what shows up on a list of Minnesota-headquartered startups. The reach of our state’s fintech network is deeper and wider than many might realize.

The Fintech Future Is Bright

“Past Minnesota startup successes are inspiring the next wave,” said Rob Weber, cofounder of Great North Ventures. “For example, Vertical Insure’s founding story had roots in youth sports because of Justin Kaufenberg’s experience in trying to find an insurance product for SportsEngine. Jeff Hinck of Rally Ventures has commented how Travelers Insurance provided a legacy example of a mega-success in embedded insurance. Another example is Andrew Johnson leaving as CRO at Branch to now lead Yardstik, a growing local firm in the workforce tech category.”

“It’s clear that fintech is entering the next major phase of innovation,” said Great North Ventures’ Ryan Weber, “with embedded finance, AI-enabled financial workflows, vertical fintech, modern credit infrastructure, insurance innovations, workforce financial services, and more. And there’s no question Minnesotans are well positioned to participate in all these sectors going forward.” Great North Ventures recently highlighted ten notable fund raises across the larger fintech industry in just the past month.

Yes, more people in our state are starting to recognize the depth of the fintech ecosystem that already exists here in our state. And Minnesota will no doubt continue to make its mark with startups, founders, and investors very much in the center of where fintech is headed next.

———

Post Script: I saw a piece from PitchBook recently in which one VC labeled fintech as a “top-5 TAM worldwide.” Yes, that big.
An Evening With a Bunch of My Heroes


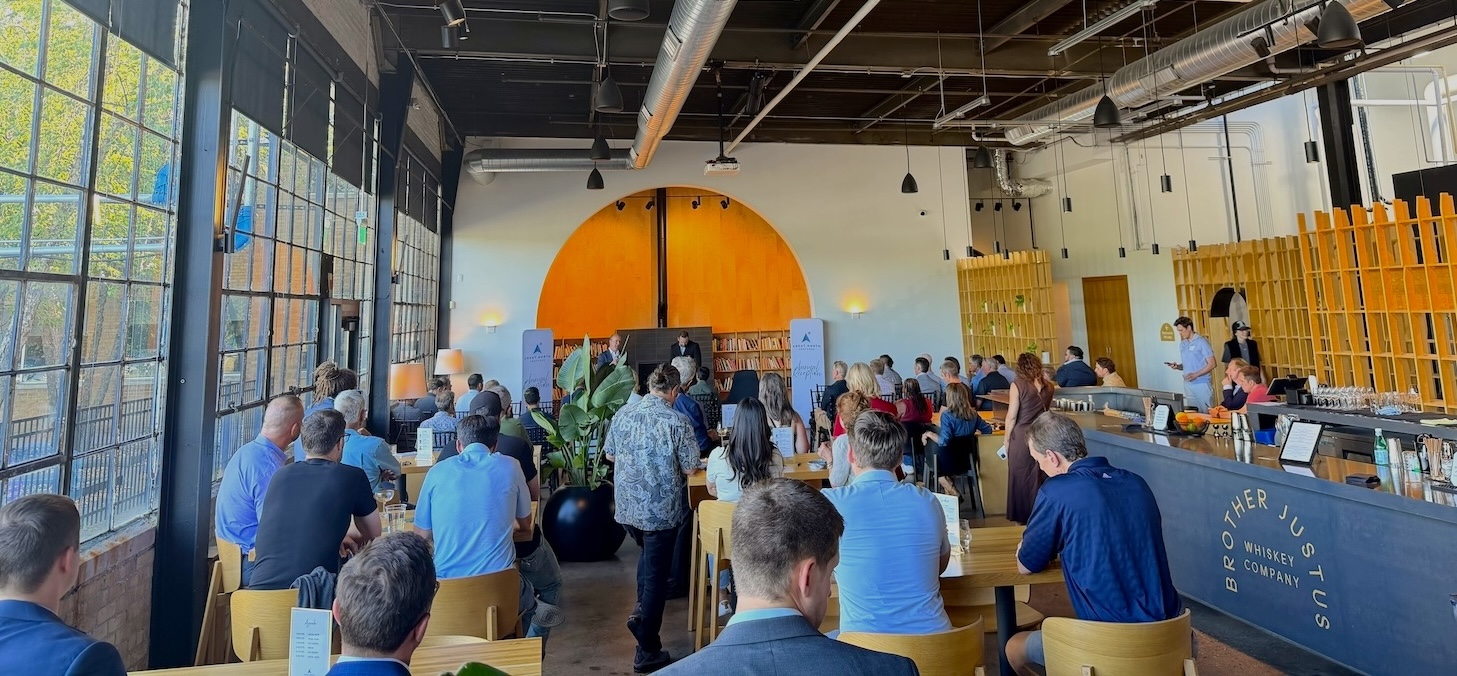
I had the privilege recently of attending the Great North Ventures annual reception. It was a wonderful experience to see and chat with so many of my favorite people, all in one room — successful founders and smart investors who’ve been a major part of building the Minnesota startup ecosystem over the years. I’m grateful to my friends at Great North for putting together such an excellent event.

Not only was the networking special — and the bites and drinks! — but Rob and Ryan Weber put together a great program as well, featuring three entrepreneurs they’ve backed over the years:

• Mynul Khan, founder and CEO of Field Nation, who shared lessons from nearly two decades of building and the compounding value of capital-efficient growth and perseverance.

• Atif Siddiqi, founder and CEO of Branch, who talked about scaling one of the country’s leading workforce payments platforms and the growing opportunity around embedded financial infrastructure.

• Nir Dremer, co-founder and CEO of CapitalOS, who shared his perspective from Stripe, Tipalti and now CapitalOS on how financial products are increasingly becoming embedded directly into the software businesses use every day.

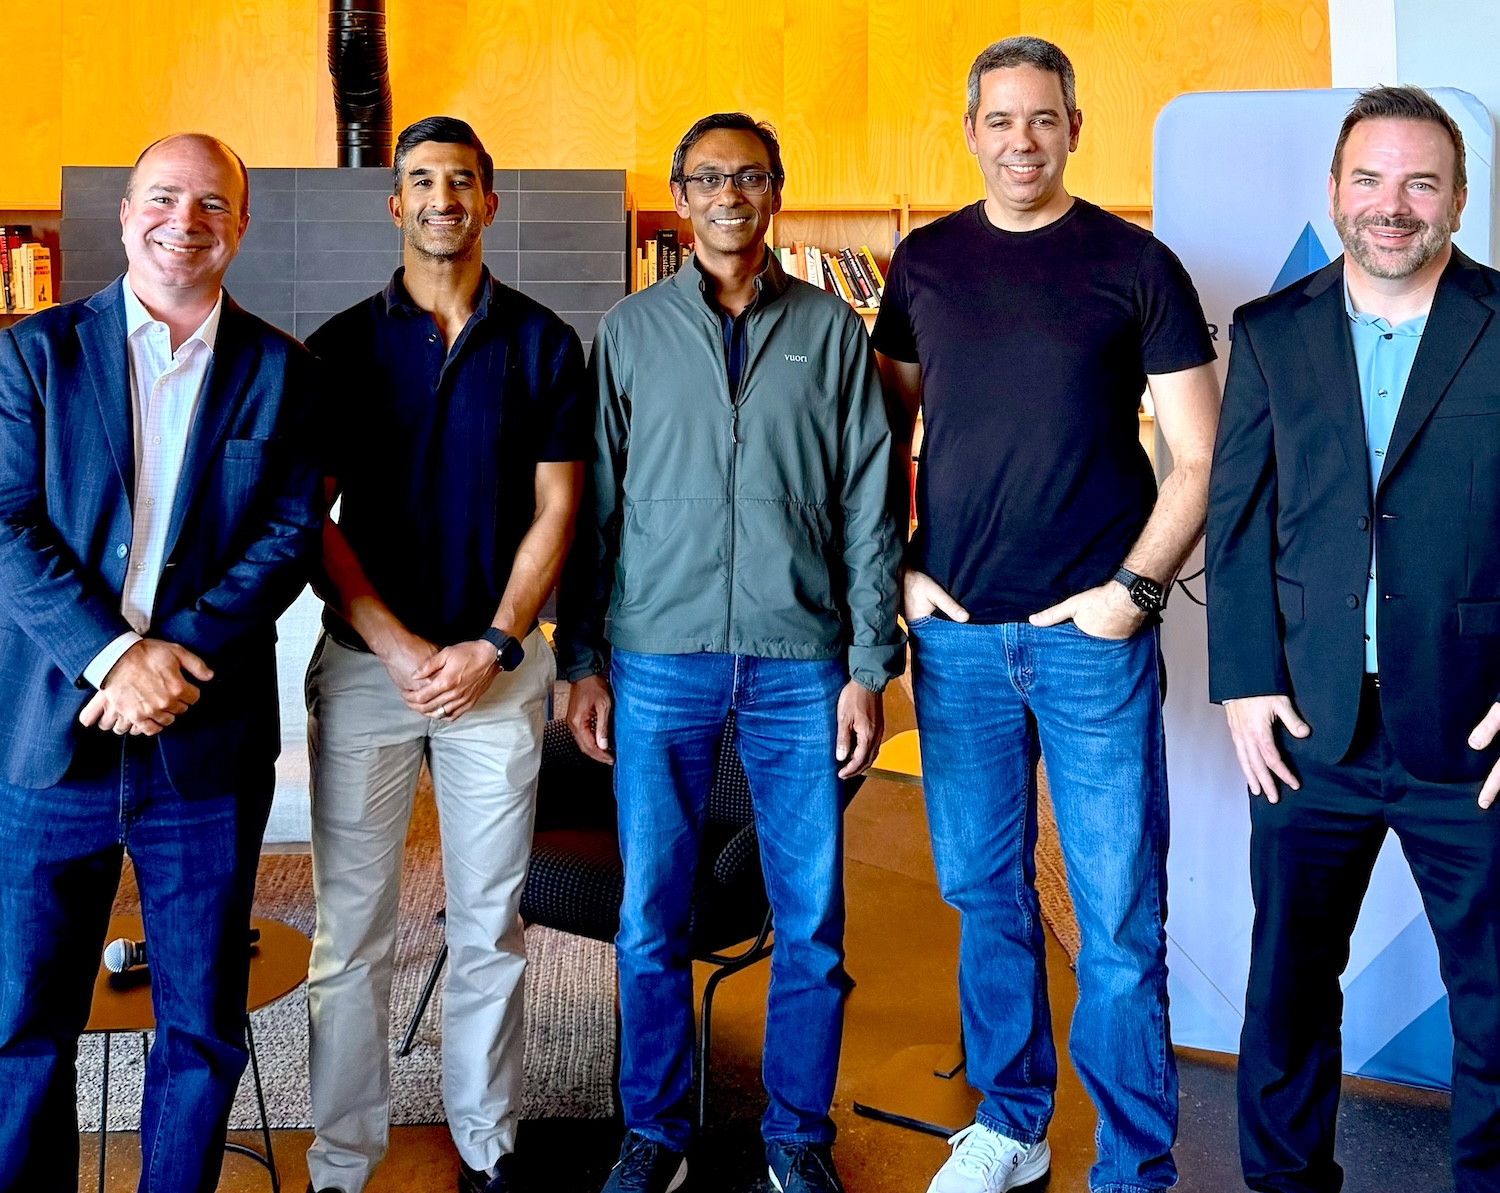
photo of five speakers at the event

Left to right: Rob Weber, Atif Siddiqi, Mynul Kahn, Nir Dremer, Ryan Weber

As Rob said in his recap of the event, “We also had the opportunity to share an update on Great North and Fund III, including why we’re particularly excited about the opportunities we’re seeing today in vertical AI and embedded financial technology. Most importantly, nights like this reinforce what we have always believed: venture works best as a network. Capital matters, but so do the relationships, introductions, operating experience and willingness to help one another along the way.”

Ryan added: “We brought together investors, founders, operators, business leaders and friends of Great North for an evening of candid conversation about building companies, navigating change, and where some of the biggest opportunities in technology are emerging.”

I was struck by Ryan’s comments about how success is so much more than just capital: “Great North has always been a network-driven fund. Some of the most valuable things we can do aren’t writing checks — they’re introducing a founder to a customer, helping someone find a critical hire, connecting investors and entrepreneurs, or bringing in another operator who has already lived through the problem.”

It’s been a great pleasure for me to be part of the Great North Ventures community for close to ten years now, and I look forward to keeping in touch with all the wonderful people I have gotten to know,

(For more, see the LinkedIn pages of Rob Weber and Ryan Weber.)


A Tribute to an American Entrepreneur

Gary Doan represented the best of any tech founder I’ve had the privilege of working with — and I’ve worked with scores and scores of  them over my three-decade+ career. Sadly, we lost Gary last week, and I feel like I’ve lost one of my best friends.

Even though I hadn’t seen him in a year or more, I had such a bond with him. We frequently chatted online… about tech, about local news, about national events. So learning of his passing was a shock to me. No – not our Gary!

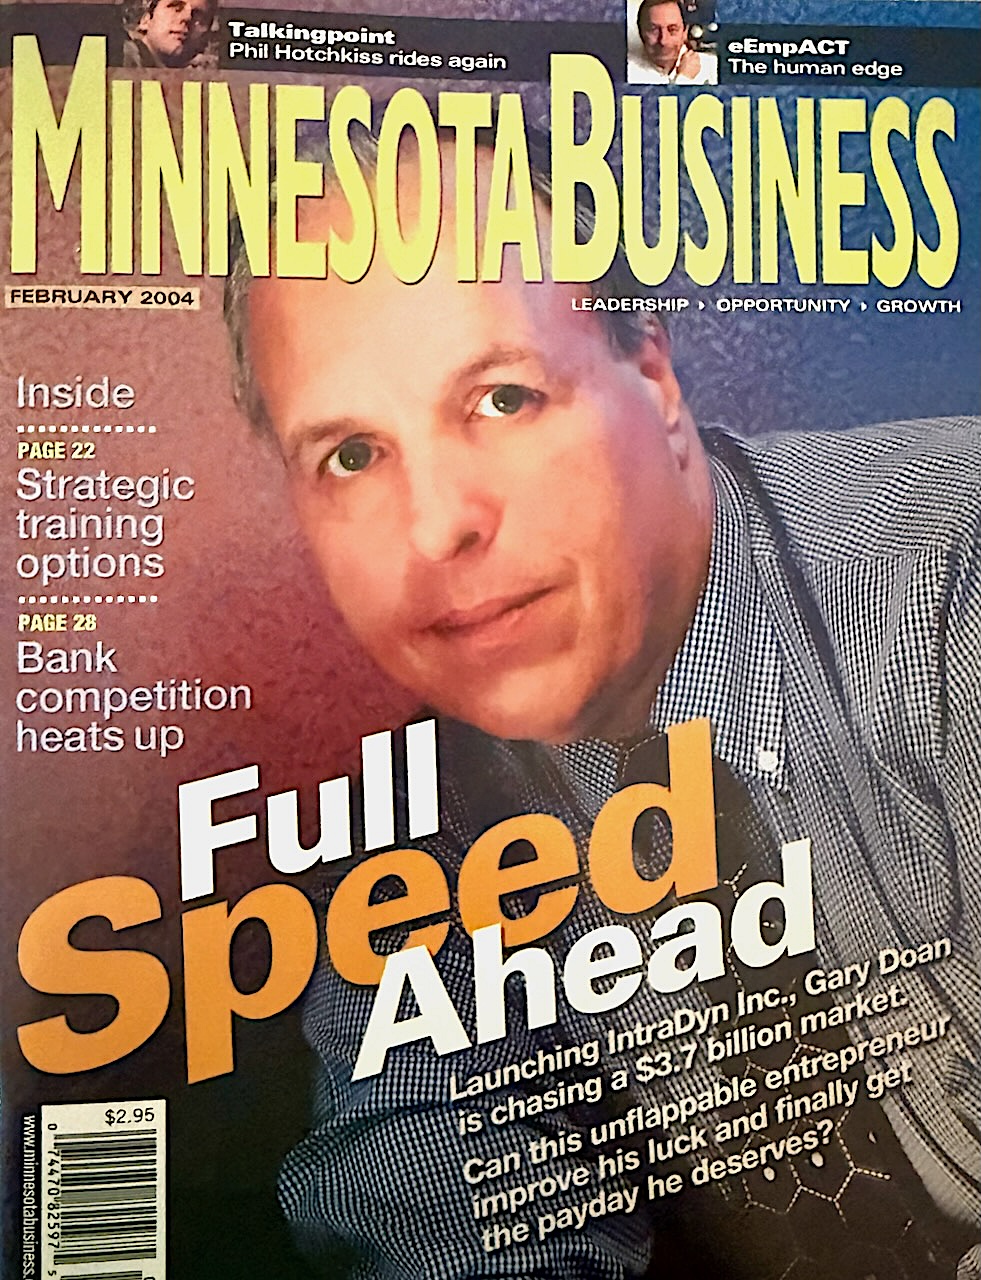
But I have many great memories and stories. I wrote a lengthy post about him on LinkedIn today. In it, I referred to a full scan of a really great cover story that appeared in our local Minnesota Business magazine. Here it is as a PDF:

GaryDoan-MNBusinessArticle-2004

(That’s the cover you see at right.) Gary had just launched his third tech startup at that point. He pulled me into that startup soon after this story, and it was an amazing experience.

Please go read that full article above, and the LinkedIn post. And do comment there on LinkedIn if you knew Gary. He was an inspiration to many!


From Bootstrapping a $70M Company to Leading a VC Fund: Lessons for Founders

Twin brothers Rob and Ryan Weber, founding partners of Great North Ventures, have raised two funds and invested in more than 50 startups to date and counting, throughout the Midwest and the rest of the county. Well before that success, however, they were founders themselves of their own ventures, beginning in their 20s, and they learned a lot the hard way in their life as “operators,” a label they proudly wear. From that experience, it’s no surprise they have actionable advice for entrepreneurs in today’s world of AI and fintech. I recently interviewed Rob and Ryan to hear some of the stories they willingly share as hard lessons for founders launching startups today.

We begin with a story from their early bootstrapping days with their startup, Freeze.com , which they founded in Minnesota in the late 1990s. “We raised an angel round of $320,000 in the spring of 2000, just before the dot-com bubble popped,” said Rob. “We were generating around $50k a month in free cashflow from advertising revenue from our prior dot-com publishing business, so we didn’t really feel we needed the cash from the angel round. However, we were excited to bring on a couple of those angel investors as board members to provide us mentorship and guidance.”

In the year after this angel round, Rob and Ryan hired their first dozen employees and were on the verge of launching their core optimization back-end system, which they had been incubating. “Meanwhile, our monthly cashflow began to decline very quickly,” said Rob, “as the majority of our ad revenues came from dot-com startups that had run out of funding. We were down to less than $100,000 in the bank and were losing money every month.”

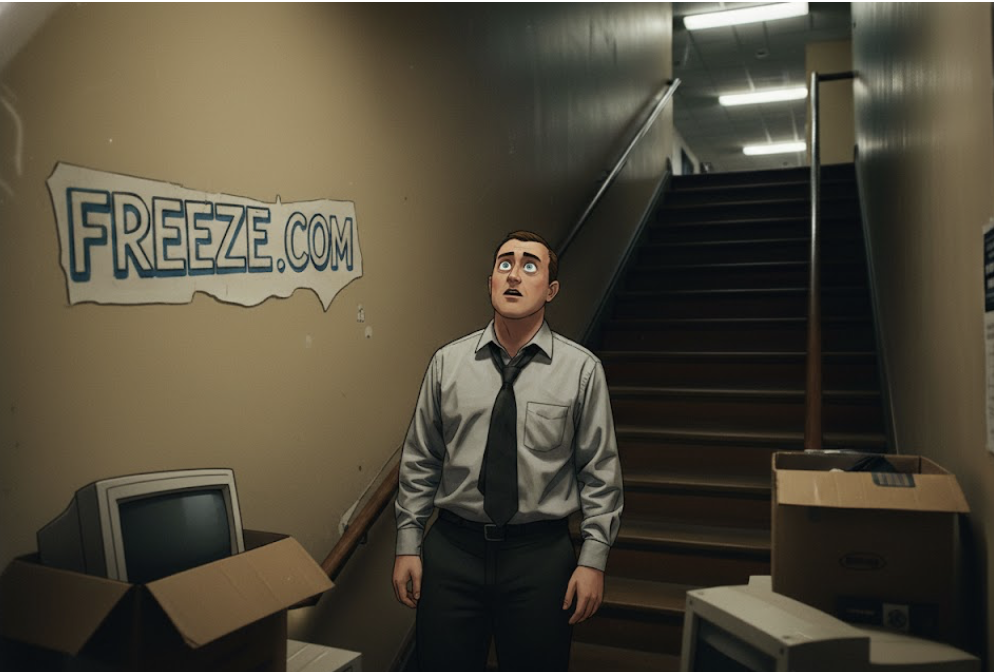
That led to a particularly mentally difficult period, Rob said. “I remember one week I couldn’t force myself to walk up the stairs to our office, and the anxiety was causing a serious lack of sleep. Luckily, I got help and worked through this very difficult time.” AI illustration depicting Rob Weber dreading to go upstairs to the office

Rob and Ryan’s board – a benefit of that angel round – advised them to reduce their operating costs and conserve cash to weather the storm. “At age 21, my brother and I had to let go a third of those first employees. It was first time we’d ever had to experience a layoff. It was hard.” However, the pair managed to launch their back-end system, and pretty quickly start to generate significantly more free cashflow with the help of their remaining team.

They were definitely back on track. “By 2005, we had scaled to $30 million in annual revenue and $5 million in EBITDA,” said Rob. I asked him what were the hard lessons he and his brother took away from that very difficult early period.

“Number one, raise cash when you don’t know if you need it,” he said. “It will be easier to do and you never know what the future will bring to your business. And, two, remember your business doesn’t define who you are. Founders sometimes lose track of this because they commit so much energy to their business.”

Because Rob and Ryan have lived the founder’s journey literally from a cold start (pun intended), and now evaluate founders for a living, they have more valuable lessons they can share to help today’s founders. The ones from the early days are especially instructive, as founders who bootstrap successfully for survival often are the ones that VCs find the most promising to fund.

Profitability Isn’t Optional, and Metrics Are Critical

Moving from survival to profitability was a journey the brothers obviously conquered. “When we were just starting out, we had pretty good aggregate metrics for our web traffic, such as how much traffic we were getting each day, from which search terms, and so forth,” said Rob. “But we had no idea how the traffic was converting and contributing to our revenue generation.” Once he and Ryan launched their optimization system, they had much better granularity as to how traffic was converting. “That allowed us to run experiments and optimize for efficiency,” said Rob. “The vast majority of our competitors had no such optimization system, so our revenue and free cashflow started to soar.”

This focus on metrics remains essential for startups today, the brothers point out. “Most lack granular KPI measurement for their businesses, which causes them to make decisions based on intuition alone,” said Ryan. “And that does not scale well.”

There’s a problem with the “growth-at-all-costs” mindset of many venture-backed companies, Rob points out. “Such heavily funded companies can get by with a poorer understanding of the KPIs that drive their business. Even though they operate inefficiently, they can continue to afford to burn lots of cash.” The key takeaway here is that founders mustbuild a fundamentally sound business first, Rob maintains. “Capital should amplify a great business, not create a temporary one.”

The Unfair Advantage of Technical DNA

Both Rob and Ryan studied computer science in college. They didn’t do coding or design work themselves once they launched their startup, “but we were very active and curious about how our team was developing our core systems,” said Rob, “and very involved in product design decisions.”

Ryan added: “Our background studying math and computer science caused us to take a pragmatic, analytical approach to decision making. I also think our technical background made us more relatable across our team. We always placed a high degree of value on technical roles, whereas some companies overvalue sales, for example.”

How involved were Rob and Ryan with their team? “We were very much ‘in the trenches’ understanding how our business was growing,” said Rob. “We were able to make effective decisions quickly. What changed over time as we scaled our business was the need to build a team that was also very entrenched in the technology aspects of our business, and to empower them to make decisions.”

The key lesson here for founders, both brothers agree, is that a deep understanding of your technology, product, and market is your most defensible asset. And having a team that also gets that is mandatory.

Scaling with Scarcity Breeds Creativity

Can a lack of resources help drive a founder to seek his or her own solutions? “We didn’t have a large enough engineering team to automate everything, so we would do a lot of tasks ad hoc,” said Rob. “One example was how we scheduled email campaigns to our opt-in email list. Because that list had grown into the millions, we couldn’t schedule one big email campaign because it would crash our email server. So, instead, for about a year in the early days, I had to break up email campaigns into a series of smaller campaigns and set an alarm to remember to check on them and start up new campaigns. This created a lot of interruption in my personal life – which basically didn’t exist! Eventually, we developed better email scheduling tools, but you do what it takes to grow – and we did.”

The brothers ran their startup – by this time named W3i, and later NativeX – with an intense focus on capital efficiency and a culture of ownership. “When others on the team see how you’re willing to accept certain hardships or personal sacrifices in growing your business,” Ryan noted, “it makes them more willing to take that on themselves. Our early team very much all had this founder mindset.”

The lesson for founders is this: Constraints can actually be a good thing. They force you to build a lean, resilient, and resourceful team.

Looking Through the Investor’s Lens: The Great North Ventures Thesis

When the Weber brothers look at a pitch now, they admit they must see past the flashy growth numbers to the underlying unit economics. “In nearly every first call,” said Rob, “I ask how much capital has been invested into the business to get to where they are now. It isn’t so much how much revenue they’re generating relative to what they’ve burned, but, rather, how much have they really accomplished with the capital that’s been invested?”

With their experience, they ask themselves: Is this a real business, or just a story the entrepreneur seeks to fuel with capital? “I once invested a small angel check into a startup that raised a Seed round pre-launch. I remember the startup burned through all the Seed capital and ultimately never even launched their product. This stuck with me. There are many ‘founders’ out there that, even if they were able to successfully raise a Seed round, still would not be able to organize a team to deliver a well-crafted product that solves a real problem.”

What smart investors like the Webers look for are founders who are obsessed with their business model and their unit economics, not just the funding they seek.

“A really good example of what we call ‘Seed-strapping’,” said Rob, “is our portfolio company WithMe, which began in Chicago, whose founder proudly admits he raised the least amount of capital necessary.”

Investing in Founder-Market Fit

How does Great North Ventures evaluate founding teams today? “I’m looking for founders who have uncovered a market tailwind that is being underutilized and, as such, have created the opportunity to solve a problem in a new way that wasn’t possible before,” said Rob. “Often, this is through the unleashing of an emerging technology where incumbents are slow to adopt.”

Rob goes on: “When Ryan and I were teenagers, in the mid-to-late ‘90s, Internet usage was exploding and, although there were many people in the world experimenting with web publishing, there was a huge imbalance. That is, the opportunity created by the rapid, widespread adoption of the Internet was far greater than the number of web publishers putting up new websites.”

Ryan adds: “Ideally, the founders we look at have been tinkering with whatever technology they plan to unleash so they have mastered the skills required to properly harness it within their business.”

Essentially, the Weber brothers back founders who have a unique, almost unfair, insight into the problem they’re solving. It’s the “Why you?” question.

“Typically, I see the unique insight coming from one of two areas: technology-driven or market-driven,” said Rob. “Founders who have mastered a new technology can often deploy their skills into any number of vertical markets, which can provide them an advantage over incumbents. Think back to the late ‘90s: no one at giant Walmart was going to take on Jeff Bezos when it came to pioneering in e-commerce, despite Bezos having no retail background. Market-driven insights can be very powerful, too, especially in more complex industries where problems are super obvious outside of the industry. When founders have a more market-driven insight but lack technical skills, that’s okay. But we strongly prefer they have a cofounder or early team member who has strong technical skills to complement them.”

Net-net, the brothers look for evidence that the founders are the only people in the world who can build this specific company.

Investing in Capital Efficiency

It’s helpful to look at how the Weber brothers view a startup’s request for capital. Just a number means little – it’s the strategic plan that matters.

“I’ve often seen that, even when startups are competing in the same market, how they deploy capital is frequently more important than the total capital raised,” said Rob. “I’ll give one example from our portfolio. We have a startup in our portfolio called Inhabitr, which was also originally founded in Chicago (but now in California). It provides an AI-powered platform for B2B furniture procurement. Around the time we led their Seed round, a handful of other competitors raised much larger early funding rounds. While Inhabitr invested in its core AI capabilities and chose to partner with others in the furniture retail space, their competitors invested heavy amounts of capital into developing their own inventory and warehouses. Over time, most of Inhabitr’s competitors significantly underperformed because of this poor deployment of capital.”

The Webers’ bootstrapping background gives then a keen eye for founders who will treat every dollar of investment with the same care they’d treat their own last dollar.

Thus, they look fora clear, credible plan for how their fund’s capital becomes a force multiplier for the founders’ existing resourcefulness.

“One thing we often see,” said Ryan, “is startups burning large amounts of capital to fund their unproven go-to-market strategy. A better approach is to deploy small amounts of capital in the early going to develop expertise in one, scalable market channel. Once they’ve mastered that channel, that’s the time to plow capital into it.”

Conclusion: The Best Founders Think Like Investors

The Webers believe, whether you’re bootstrapping or raising millions, the goal is the same: build a durable, valuable company. They know the best founders are always thinking about the long-term health and defensibility of their business.

What final piece of encouragement would Rob and Ryan add? They jointly advise: “Cultivate an unwavering focus on your customers and the problem you’re solving, and let that guide you in key decisions. The investment you make into systems that allow you to understand your customers at the most granular level will likely be your most profitable investment.”

If you’re a founder building with this mindset, and you’re a fit for Great North Ventures’ investment strategy, Rob and Ryan want to hear from you.

To learn more about Rob and Ryan Weber’s background, check out my prior post here.

———-

Note: This post first appeared on the Great North Ventures website, with my byline, and here’s my bio that appeared with it:

Graeme Thickins is a startup advisor and an investor in Great North Ventures Fund I. He is also an angel investor in two subsequent Great North portfolio companies. He has written previously for and about Great North Ventures and its founders over several years.


MN Entrepreneurs and the Fortune 500 – A Look Back to One of My Favorite Posts

graphic showing the state map of Minnesota with the words Fortune 500 over itI’ve been writing about Minnesota startup founders for a long time. I can’t remember the first post I wrote about one — probably sometime in 2006. But I do know I’ve penned innumerable such posts over the years. One of my favorite recurring subjects was Robert Stephens, founder of The Geek Squad. I did a search recently to unearth just how many times I wrote about him. It was twelve! Yes, that many posts about just one of our state’s many successful tech founders! Why?  I guess because he was such a fascinating and quotable guy — and of course because I admired his success. Some of my posts about Robert were lengthy features, while others just mentioned his participation in certain local events. Here’s my list of all those posts.

What does Robert have to do with the Fortune 500? His firm was acquired by one: Best Buy. Which you surely know if you live here. And both firms were, of course, founded right here in Minnesota. The significance of his acquisition cannot be overstated: it became the basis of a massive services business for Best Buy, which continues to this day.

My favorite post about Robert was headlined and dated thusly:

text of the headline of Graeme's favorite post about Robert Stephens

Why does this one stand out for me? Because it isn’t just about one of my favorite founders, but also one of my favorite topics: branding. I re-discovered what a great read it was (if I do say so myself!) when I went back to it after so many years. (Warning, it’s a long one.) The full post is here.

Speaking of Fortune 500 firms here in Minnesota… some years after the above, I wrote a commissioned piece on this topic: “Minnesota Has Long Had a High Per-Capita of Fortune 500s. How’s That Working Out?” I didn’t write about Best Buy in that one, but I did quote at least one other Minnesota founder, whose firm was acquired by a Fortune 500 — for close to a billion dollars.

Recently, I was reminded that I only focused on Twin Cities-based Fortune 500s when I wrote that article. How could I have forgotten an out-state Fortune 500: Fastenal, founded and based in Winona MN to this day.. No, it isn’t a very high-tech company, but what an amazing growth story it has been over the years! The recent passing of its iconic founder and CEO, Bob Kierlin, reminded us all of that. I just posted on LinkedIn about him. Some of his very wise words were included there.

The lesson in all of this? Minnesota grows some great ones!


« Older posts