Reflections & analysis about innovation, technology, startups, investing, healthcare, and more .... with a focus on Minnesota, Land of 10,000 Lakes. Blogging continuously since 2005.

Category: Startups (Page 1 of 30)

How Minnesota Is Making Its Mark In the Fintech Industry

We Ask Several Notable State Names to Weigh In

(Note: This post first appeared in Next In The North.)

Minnesota has been a center for financial services for decades. You know the names – big banks, wealth management firms, capital markets players, giant insurance companies – most still with a significant presence here. But where are we today in our state now that new financial technologies are flooding into the daily lives of consumers and businesses everywhere?

We collectively call this new industry “fintech,” but it’s made up of many sectors – banking, payments, lending, wealth management, insurtech, and more. Minnesota has several growing fintech firms already making a big mark, and several more startups are breaking out.

“The growth of fintech is an interesting pattern of companies using financial technology to solve very practical problems for workers, families, small businesses, and industries that historically have not been well served by financial products or modern software,” said Ryan Weber, cofounder of Great North Ventures. He cited areas such as faster access to wages, better insurance access, financial tools embedded into workforce platforms, products for small-business money management, and other applications where better financial infrastructure creates both economic value and better customer outcomes.

A Minnesota venture capital firm that’s a well-known leader in fintech investing is Rally Ventures. “Fintech and, more broadly, regulated financial industries, form the basis of the Rally Ventures AI+ thesis — previously SaaS+,” said Justin Kaufenberg, managing director. “We’ve been focused on this theme since inception. When your core economic engine is the credit card payment, the insurance policy, the background screen, the loan product, the payroll product, or the funds distribution service, it means you can irrationally invest the underlying platform. The customer feels fortunate to receive such a robust platform, at such an affordable price. We disrupt the incumbent financial institutions, allowing us to delight the customer. Done correctly, it is nearly impossible for a traditional software/Ai company to compete.”

A Fertile Training Ground

John Stavig is Managing Director of the Gary S. Holmes Center for Entrepreneurship at the U of MN Carlson School of Management. “I don’t believe we’ve realized our full potential, given the innovation capacity of the local banks and insurance companies. This is one of the reasons Plug and Play has brought their accelerator programming to the Twin Cities, through the support of Allianz, Bremer Bank, and others.”

I asked him what Minnesota fintech companies especially stand out for him. “Sezzle is a tremendous local success story with a market cap approaching $4 billion. What started out as an early BNPL company has continuously innovated to develop lasting relationships with younger consumers by helping them manage convenient digital credit services,” Stavig said. “Branch is another innovative fintech that started with workforce scheduling and evolved into a financial services provider for hourly employees.”

Stavig’s involvement with the MN Cup startup competition gives him a special perspective. “In addition to Sezzle’s past participation, we’ve had several payment processing companies, such as Mozrt, participate in in recent years.” Do startups have an edge in fintech specifically? “They seem to be able to more quickly pursue niche opportunities that can turn into attractive acquisition candidates for slower-moving corporations. Given their legacy platforms and customer base, the big financial corporations seem better positioned to acquire, rather than build, new technology platforms.”

Stavig sees Carlson School students’ fintech interest firsthand. “I just came from a class where students were discussing a number of challenges with financial literacy and personal credit management. It’s definitely an area where they see opportunities for improvement.”

He called out another MN Cup startup from this year’s Impact Division: Duome. “They’re very early, but ambitiously taking on the big issue of housing affordability.”

Our universities in Minnesota have produced several successful fintech founders, certainly including the two who launched the aforementioned Sezzle, Charlie Youakim and Paul Paradis, both U of MN Carlson School MBAs; another founder, Brandon Dols, a St. Cloud State grad, founded Figg, which was acquired by JPMorgan.

It’s also true that many Minnesota university grads, now employees at local fintech startups, cut their teeth in the financial services business here by having previously worked at our locally based big banks or insurance companies.

Fintech startups can pop up anywhere, including outside the Twin Cities metro area. Susan Sorensen Langer studied at the U of MN Carlson School and began her career at USBank. She went on to become founder and CEO of Spave, which is based in Red Wing, Minnesota. Spave is a social giving app that empowers individuals, employers, and nonprofit partners to automate saving and giving through everyday spending.

Myles Shaver is a Professor and Curtis L Carlson Chair in Corporate Strategy at the U of MN Carlson School. “Our region has the ingredients to be a player in fintech,” he said. “The banking systems that grew into Well Fargo, from Norwest Bank, and US Bank both originated here, as did other financial institutions such as IDS and St. Paul Companies. Because we’re a business center where finance is important, combined with our history in software and computing, that gives Minnesota the talent base to help found and grow fintech.”

He too noted that Carlson School students have clear interest in new financial technologies. “It does make its way into our classes. The success of fintech often comes from relaxing frictions or capitalizing on blind spots in the current banking system. So, understanding those fundamentals will always be key and a part of our curriculum.”

Shaver said he’s sure all major financial institutions are experimenting with fintech to some degree. “The outside view that startups bring is often key in something like this and can lead the banks to augment their internal development with acquisitions,” he added.

Fintech Founders Speak Out

I sought comment for this article from three Minnesota entrepreneurs who have achieved notable success:

• Brock Noland cofounded pH Data in 2014 to build intelligent systems for enterprises, to help form the foundations AI depends on. It has grown to roughly 930 employees worldwide after raising just $2.5 million in disclosed venture funding, prior to a 2024 investment/acquisition by private-equity firm Gryphon Investors. In 2022, Noland cofounded Vertical Insure to help industry-specific, vertical SaaS companies increase profits through embedded insurance. It was just named to FinTech Global’s 2026 InsurTech100.

What’s Noland’s take on the current state of fintech in Minnesota? “I think we’re seeing a real renaissance of fintech in Minnesota,” he said. “I use a pretty broad definition of fintech that includes vertical software companies that monetize through fintech, along with pure-play fintechs like Vertical Insure. I think we have some of the best investors in this space in the country, and there’s a growing group of founders building fintech businesses here.” Has Minnesota been a good place to be? “We’ve attracted great people and raised capital from great investors. Minnesota has been a very good place for us to build.”

Who are some people in fintech here in Minnesota that he admires? “I think what Justin Kaufenberg and Jeff Hinck are doing through ‘Rally Built’ is really interesting. They’re aggressively founding and supporting new fintech businesses here in Minnesota, which I think is great for the ecosystem.”

I also asked Noland what trends in fintech he’s finding most interesting right now. “In my broader definition of fintech, I include software companies that monetize through financial products. Traditionally, that has mostly meant payments, either taking cards or providing cards, and relatively few companies have succeeded outside of that,” he said. “But that’s changing. In our business, we’re seeing software companies generate substantial margin by embedding insurance, lending, and other financial products directly into their platforms. The key is doing it in a way that makes sense for the customer and the transaction. I think it took the market a while to figure out how to do that successfully, but it’s definitely real now.”

Noland also had thoughts about raising money in Minnesota. “I think it’s a great time to raise capital for fintech companies here, and it’s gotten easier as the ecosystem has matured. Local investors are very savvy about fintech and there are more people here who understand these business models and what it takes to build them.”

Noland noted that most of Vertical Insure’s early funding came from local investors, including Rally Ventures, Groove Capital, Dundee, and local angels. “Greenlight Re was our primary investor outside of Minnesota and is also a strategic investor,” he said. “More recently, we brought in Updata Partners as we entered our next stage of growth.”

• Cale Johnston founded ClickSWITCH in 2013 to help banks simplify the process of bringing new account holders onboard quickly and efficiently. It was acquired in 2021 by Q2 Holdings for $65 million. In mid 2025, Johnston founded Onsetto as a commercial banking operating platform, which offers several relationship-building benefits for banks with business customers. including an offering called “SwitchAssist.” In just a year, Onsetto has raised $11 million. “Last year at this time, we had zero customers,” Johnston said. ”We now have 50 under contract, and 30 of them are live.”

What does he like about being in Minnesota? “You can run a leaner, more efficient company here. You can retain more equity as a founder. Dilution on the coasts makes that harder, not to speak of the high cost of labor there.”

Johnston said Onsetto has been targeting smaller community banks, especially those focused on small business. His experience with large banks in the past is that it can take up to two years to do a deal. “Fostering relationships over time has to be the focus there.” (At his previous startup, ClickSWITCH, Citi Bank was a customer.) He said community banks move faster, and that “big banks tend to want to build versus buy.” Locally, he named Associated Banks, Tradition Capital, Bridgewater Bank, and Bell Bank as being approachable and open to new innovations. Associated has identified Minneapolis as a growth market, and is now the ninth largest bank by deposits in the Twin Cities.

What challenges does a new fintech company face? Johnston named two: “Can you sell? And can you get them live?” With Onsetto, he said, “We’re there.”

• Michael Noble cofounded Apruve in 2013 to develop a cloud-based platform to automate business-to-business (B2B) credit, invoicing, and accounts receivable management. Its technology enabled manufacturers, distributors, and other B2B suppliers to offer customers flexible payment terms without having to manage credit risk or collections themselves. Apruve raised approximately $8.25 million in VC funding and, in December 2022, announced it was being acquired by TreviPay for an undisclosed amount. TreviPay operates a global B2B payments and invoicing network and, at the time, was processing approximately $7 billion in annual transactions across 32 countries.

I asked Noble if there was any advantage in being based in MN when he was building Apruve. “We found talented people for less, and it was less competitive to keep them around,” he said. “We never did consider moving. Being in the middle of the country is convenient for getting to both coasts.”

What about raising money as a fintech startup? “It’s always hard,” Noble said. “I like the narrowness of fintech as there are only certain investors or funds that focus there. Minneapolis is a decent banking community, so I think there is always optimism for new innovations in and around moving money.”

Noble said 100% of the money Apruve raised came from out of state, except for “a few early angels.” What did Noble say about his successful exit of Apruve to TreviPay? “It was a good exit to a company that really treated our employees well and had a great culture, which is something you don’t often hear.”

No article on Minnesota fintech would be complete without also including Minneapolis-based Branch. Atif Siddiqi founded the company in 2015 in California, then moved it to Minnesota after participating in the inaugural Techstars + Target retail accelerator program in 2016. The company’s original product was a mobile B2B scheduling and messaging app to allow retail and hospitality workers to digitize their work calendars and coordinate shift swaps. But working with hourly and gig workers, Branch learned that scheduling was only part of the problem. Shift workers faced financial stress and irregular income due to traditional bi-weekly pay cycles. So, in 2018, it pivoted. Partnering with Mastercard and Evolve Bank & Trust, it added “earned wage access” by making a fee-free debit card part of the app. It has since partnered with major backend networks like Stripe. All told, Branch has raised $133 million to date, including from Minnesota-based funds. It’s grown to more than 290 employees and has seen more than $28 billion in instant payouts issued to workers via its Branch Cards.

Influence Well Beyond Our State Borders

The impact of Minnesotans in fintech includes much more than companies headquartered here. Technologists with Minnesota roots who went on to play major roles at significant new financial services companies nationally include Jeremy Allaire, founder and CEO of crypto stablecoin leader Circle; Alex Cram, Director of Software Engineering at Bill.com; and Dan Titcomb, founder of Provide. There are doubtless other Minnesota ex-pats that would illustrate the influence our local ecosystem has on the larger fintech industry, certainly more than what shows up on a list of Minnesota-headquartered startups. The reach of our state’s fintech network is deeper and wider than many might realize.

The Fintech Future Is Bright

“Past Minnesota startup successes are inspiring the next wave,” said Rob Weber, cofounder of Great North Ventures. “For example, Vertical Insure’s founding story had roots in youth sports because of Justin Kaufenberg’s experience in trying to find an insurance product for SportsEngine. Jeff Hinck of Rally Ventures has commented how Travelers Insurance provided a legacy example of a mega-success in embedded insurance. Another example is Andrew Johnson leaving as CRO at Branch to now lead Yardstik, a growing local firm in the workforce tech category.”

“It’s clear that fintech is entering the next major phase of innovation,” said Great North Ventures’ Ryan Weber, “with embedded finance, AI-enabled financial workflows, vertical fintech, modern credit infrastructure, insurance innovations, workforce financial services, and more. And there’s no question Minnesotans are well positioned to participate in all these sectors going forward.” Great North Ventures recently highlighted ten notable fund raises across the larger fintech industry in just the past month.

Yes, more people in our state are starting to recognize the depth of the fintech ecosystem that already exists here in our state. And Minnesota will no doubt continue to make its mark with startups, founders, and investors very much in the center of where fintech is headed next.

———

Post Script: I saw a piece from PitchBook recently in which one VC labeled fintech as a “top-5 TAM worldwide.” Yes, that big.
An Evening With a Bunch of My Heroes


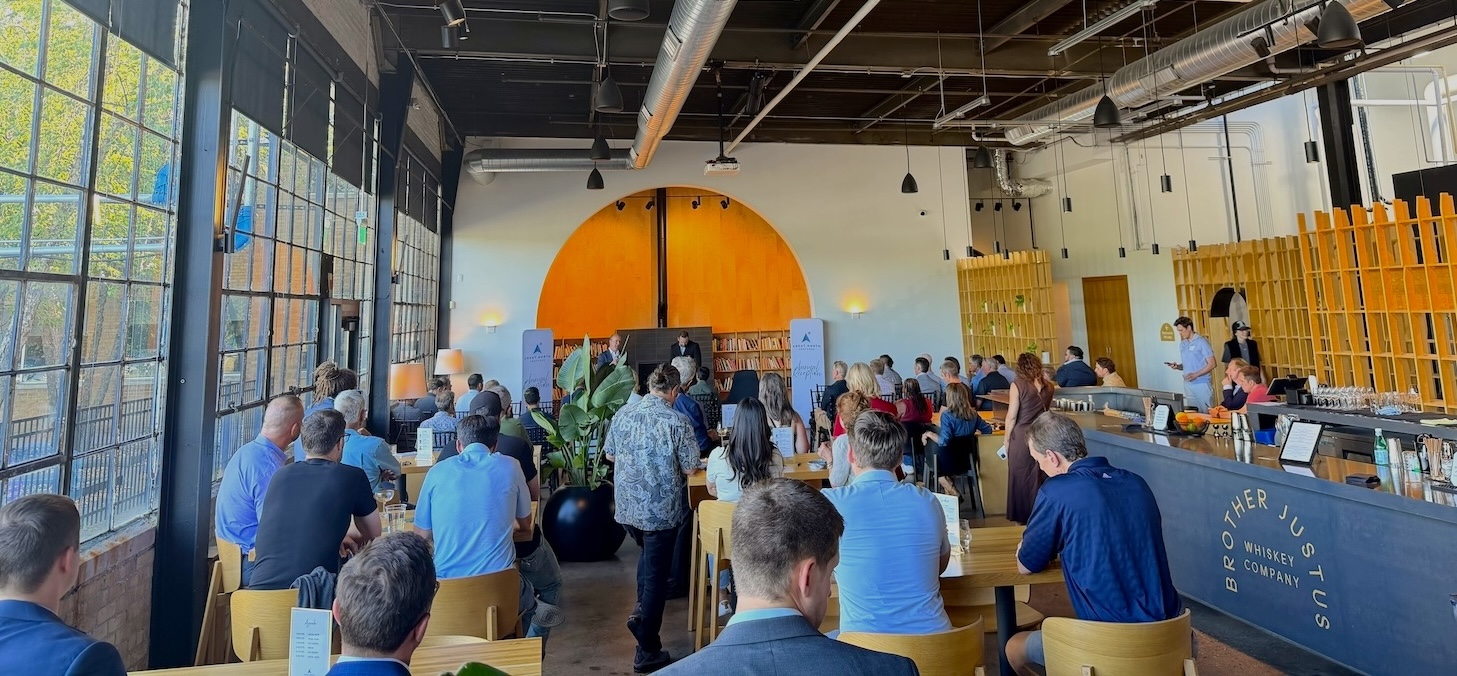
I had the privilege recently of attending the Great North Ventures annual reception. It was a wonderful experience to see and chat with so many of my favorite people, all in one room — successful founders and smart investors who’ve been a major part of building the Minnesota startup ecosystem over the years. I’m grateful to my friends at Great North for putting together such an excellent event.

Not only was the networking special — and the bites and drinks! — but Rob and Ryan Weber put together a great program as well, featuring three entrepreneurs they’ve backed over the years:

• Mynul Khan, founder and CEO of Field Nation, who shared lessons from nearly two decades of building and the compounding value of capital-efficient growth and perseverance.

• Atif Siddiqi, founder and CEO of Branch, who talked about scaling one of the country’s leading workforce payments platforms and the growing opportunity around embedded financial infrastructure.

• Nir Dremer, co-founder and CEO of CapitalOS, who shared his perspective from Stripe, Tipalti and now CapitalOS on how financial products are increasingly becoming embedded directly into the software businesses use every day.

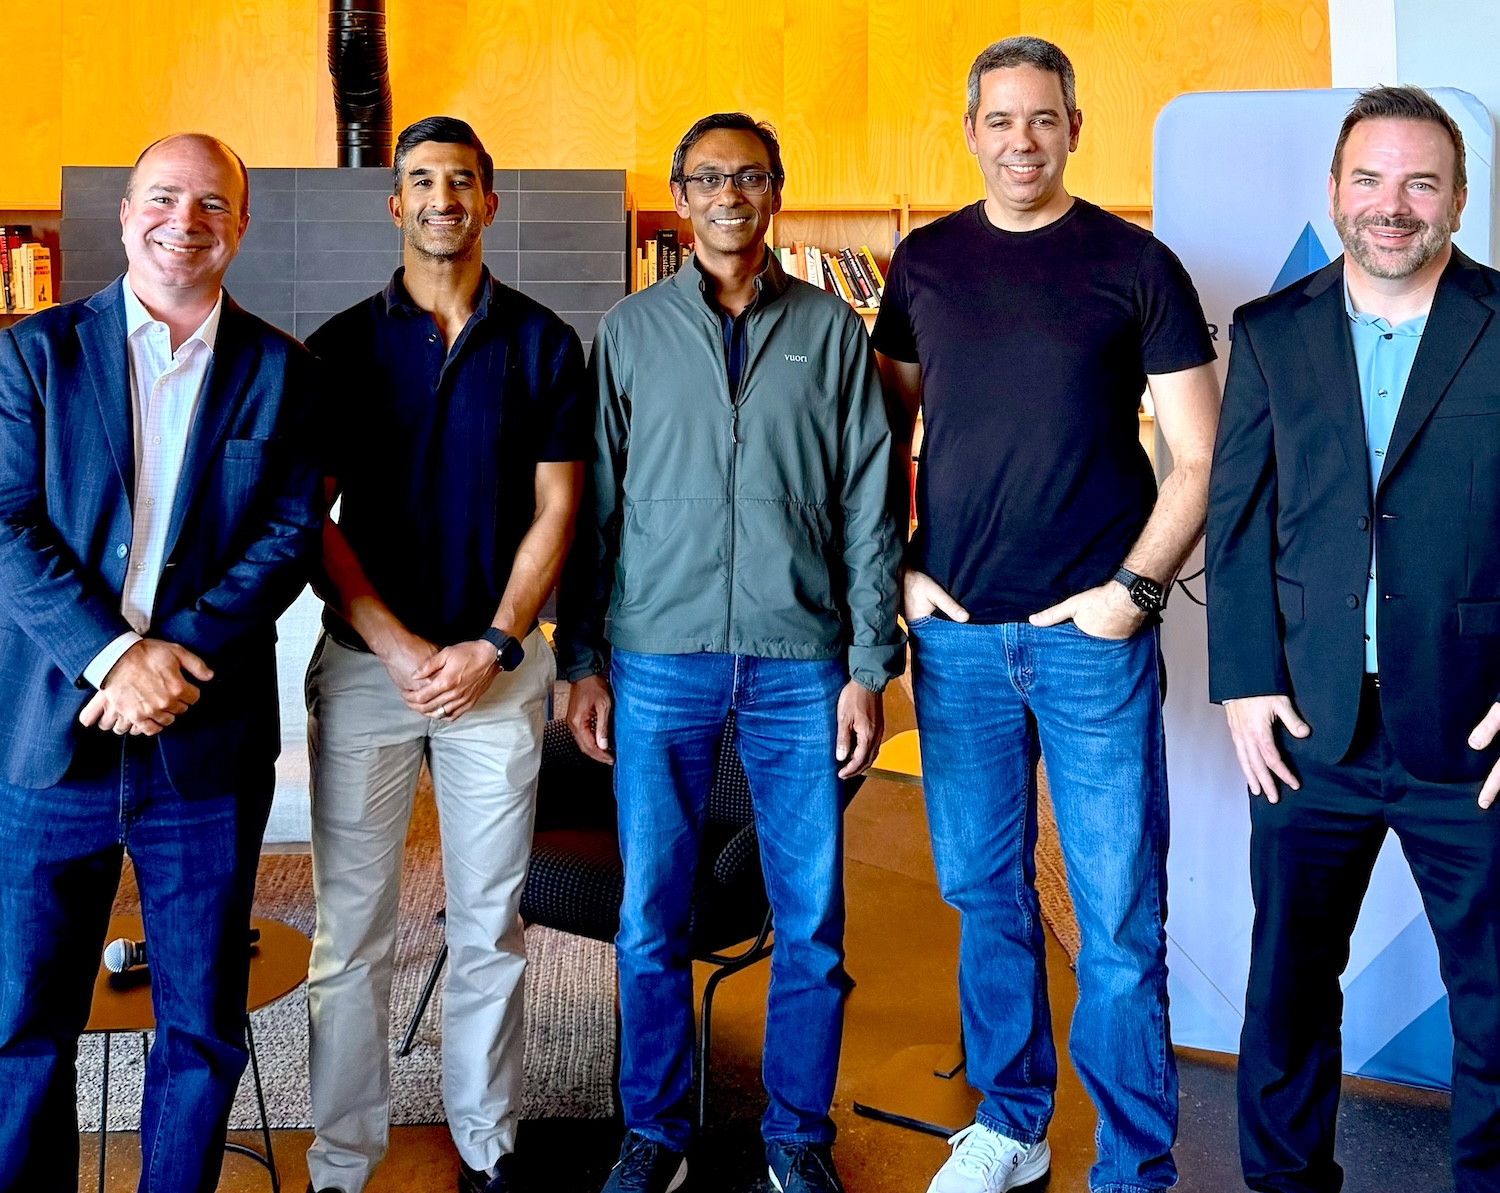
photo of five speakers at the event

Left to right: Rob Weber, Atif Siddiqi, Mynul Kahn, Nir Dremer, Ryan Weber

As Rob said in his recap of the event, “We also had the opportunity to share an update on Great North and Fund III, including why we’re particularly excited about the opportunities we’re seeing today in vertical AI and embedded financial technology. Most importantly, nights like this reinforce what we have always believed: venture works best as a network. Capital matters, but so do the relationships, introductions, operating experience and willingness to help one another along the way.”

Ryan added: “We brought together investors, founders, operators, business leaders and friends of Great North for an evening of candid conversation about building companies, navigating change, and where some of the biggest opportunities in technology are emerging.”

I was struck by Ryan’s comments about how success is so much more than just capital: “Great North has always been a network-driven fund. Some of the most valuable things we can do aren’t writing checks — they’re introducing a founder to a customer, helping someone find a critical hire, connecting investors and entrepreneurs, or bringing in another operator who has already lived through the problem.”

It’s been a great pleasure for me to be part of the Great North Ventures community for close to ten years now, and I look forward to keeping in touch with all the wonderful people I have gotten to know,

(For more, see the LinkedIn pages of Rob Weber and Ryan Weber.)


A Tribute to an American Entrepreneur

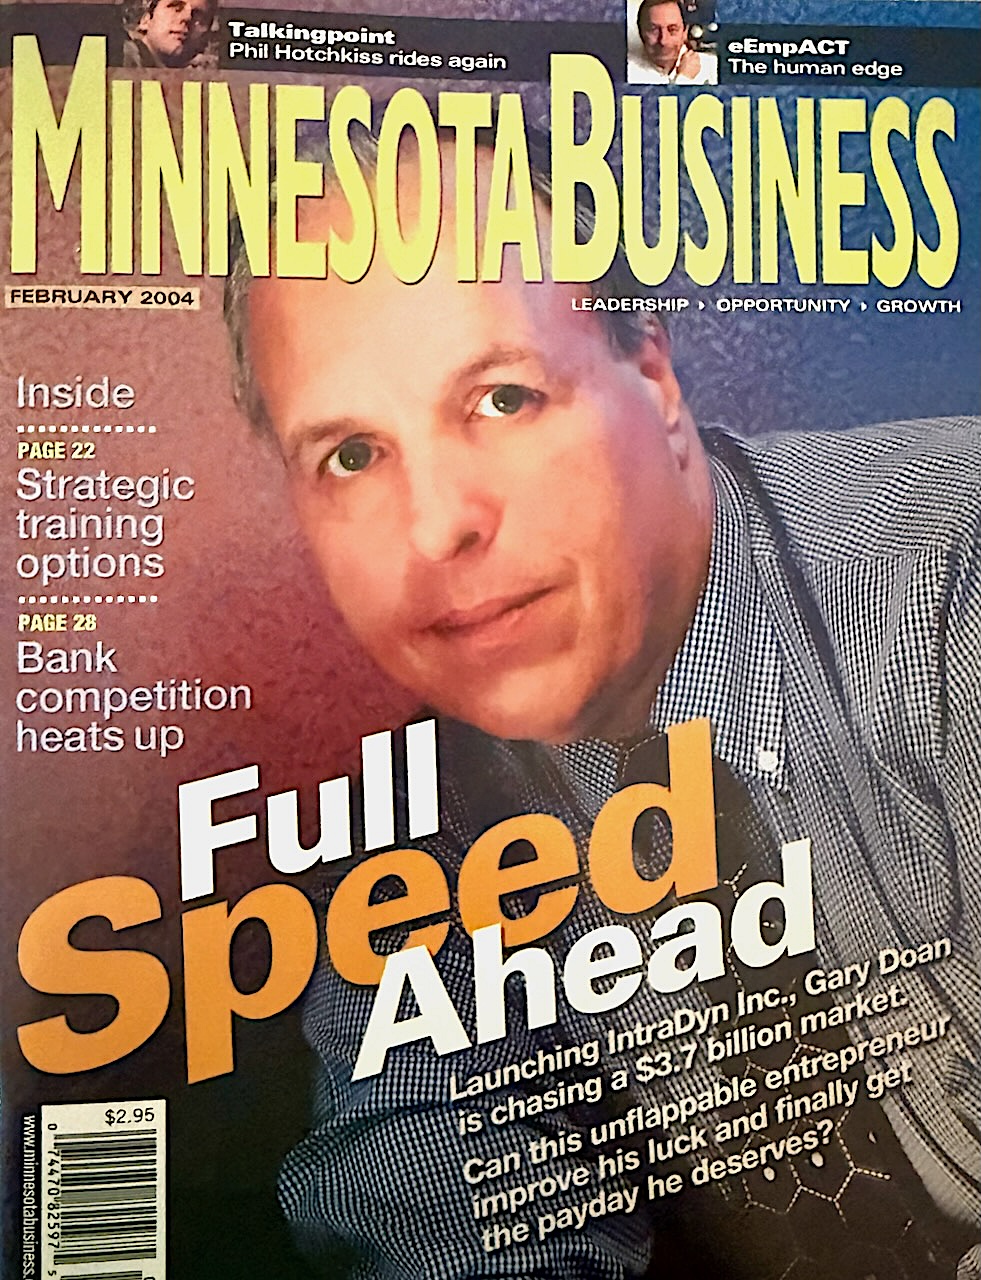
Gary Doan represented the best of any tech founder I’ve had the privilege of working with — and I’ve worked with scores and scores of  them over my three-decade+ career. Sadly, we lost Gary last week, and I feel like I’ve lost one of my best friends.

Even though I hadn’t seen him in a year or more, I had such a bond with him. We frequently chatted online… about tech, about local news, about national events. So learning of his passing was a shock to me. No – not our Gary!

But I have many great memories and stories. I wrote a lengthy post about him on LinkedIn today. In it, I referred to a full scan of a really great cover story that appeared in our local Minnesota Business magazine. Here it is as a PDF:

GaryDoan-MNBusinessArticle-2004

(That’s the cover you see at right.) Gary had just launched his third tech startup at that point. He pulled me into that startup soon after this story, and it was an amazing experience.

Please go read that full article above, and the LinkedIn post. And do comment there on LinkedIn if you knew Gary. He was an inspiration to many!


The Unconventional Path That Took a Small Midwest Startup to a Multi-Billion-Dollar Fintech Success

Its founders met at MBA school, faced some scary challenges over the years, but kept their eye on the consumer. Now valued at $3.5B+ on the Nasdaq, Sezzle isn’t done yet embedding value into its app and platform.

(Note: This post first appeared on the blog of Great North Ventures.)

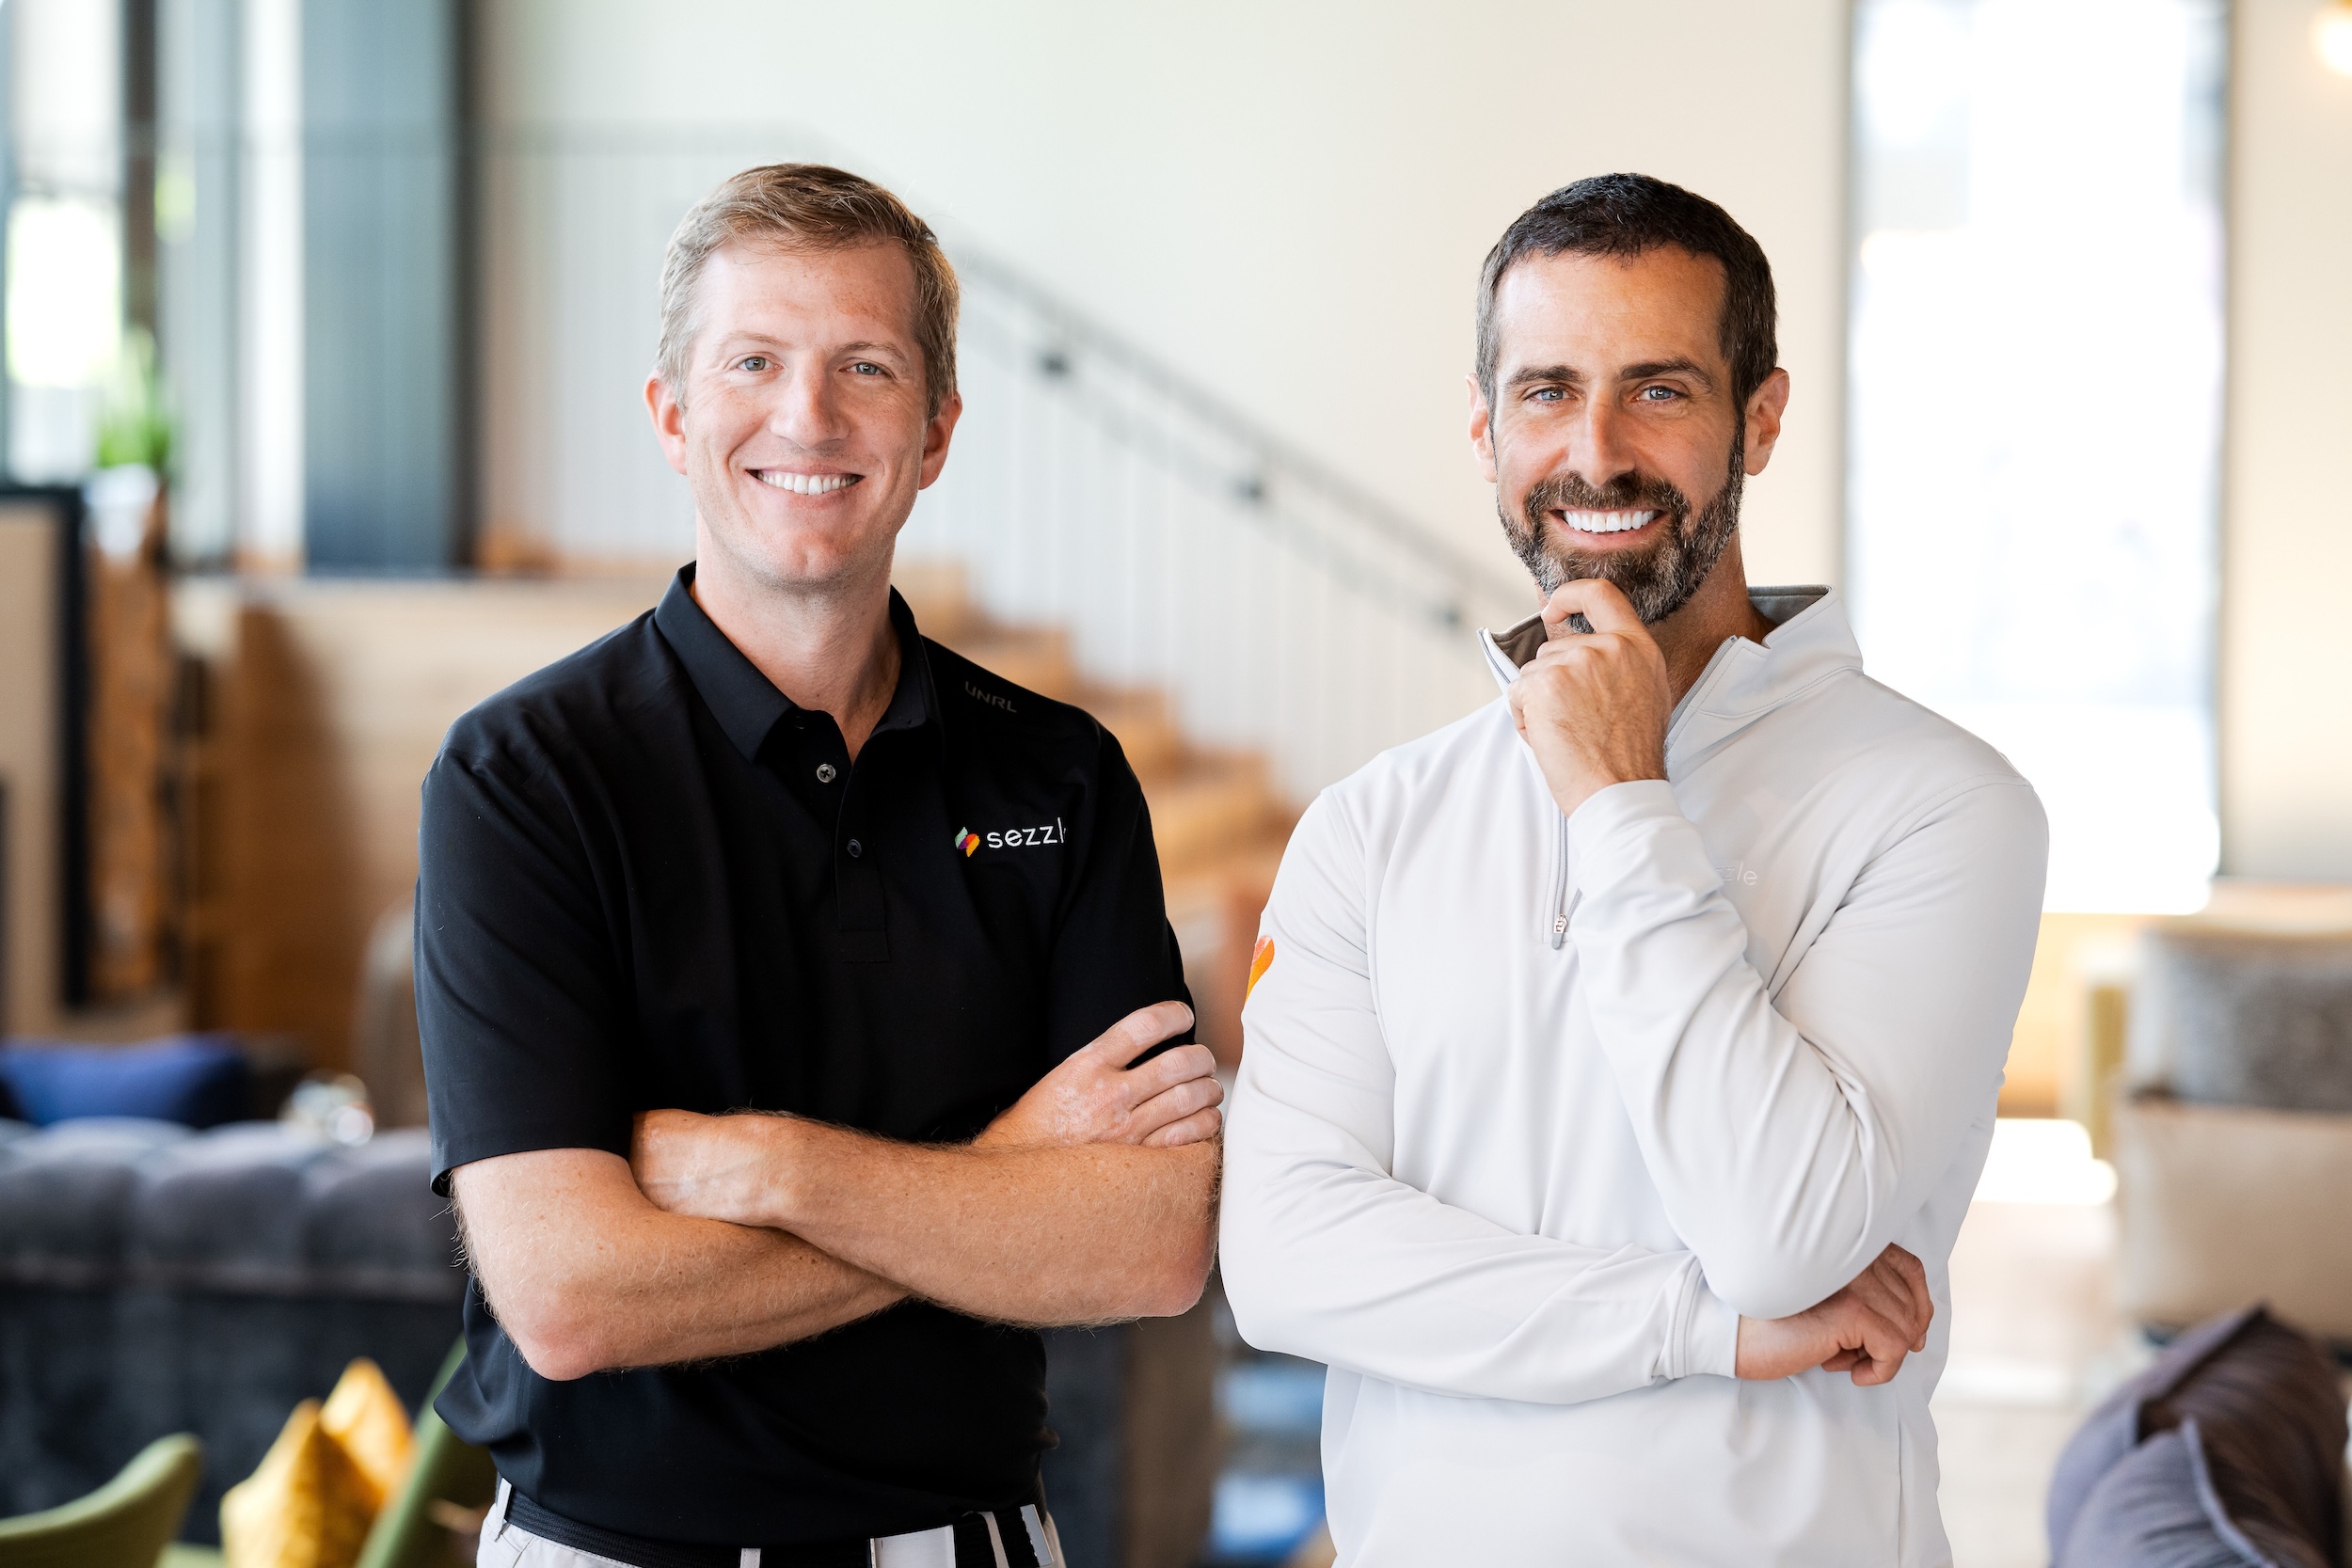
image of the two Sezzle cofounders

Paul Paradis (left) and Charlie Youakim, Sezzle cofounders.

I first met cofounders Charlie Youakim and Paul Paradis in 2016, just months after they had launched Sezzle. They were part of a pitch session I’d organized at a conference held at the University of Minnesota Carlson School of Management, the very place where they’d earned their MBA degrees six years earlier. Of the six early-stage Minnesota startups pitching that day, three went on to significant success, as I wrote recently. But none quite like Sezzle. The name, by the way, is a combination of “sell” and “sizzle” – and indeed they have.

This is a story about their journey over the ten years since, as related to me by Paul Paradis, Sezzle cofounder and president, with whom I had the pleasure of reconnecting at a founders dinner sponsored by Great North Ventures. Soon after, I arranged a sit-down with him to hear about many of the fascinating moments from the eventful journey of this super-successful startup.

“Sezzle in many ways is putting Minnesota’s fintech scene on the map,” said Rob Weber, managing partner of Great North Ventures. “And there are several more emerging embedded fintech startups focusing on a variety of markets that certainly can be inspired by their story.”

The Sezzle story begins with how Paul met and bonded with his cofounder, Charlie Youakim, the company’s CEO.

The Ping-Pong Partnership
Long before Sezzle became one of Minnesota’s most successful technology companies – and eventually a publicly traded Nasdaq fintech valued in the billions – its two cofounders were simply graduate students at Carlson trying to navigate one of the most chaotic economic periods in modern history.

Paradis and Youakim met at Carlson between 2008 and 2010, right in the middle of the financial crisis. Paradis recalls professors abandoning their planned curriculum to discuss the real-world collapse unfolding in front of them.

“All of our finance classes, the teacher would say, ‘Put your books away. We’re just going to talk about what’s going on right now,’” Paradis said. They had an education in finance they weren’t expecting when they signed up.

The two became close while working together in Carlson’s Consulting Enterprise program on a project for the Itasca Project, studying employment growth in the Twin Cities region. But it wasn’t just classroom collaboration that bonded them. “We became really good friends and ended up just becoming ping-pong obsessed,” Paradis said. “We would just play ping pong all the time together.”

Those early years also shaped their entrepreneurial instincts. Jobs were scarce. Internships had dried up. Traditional career paths suddenly looked fragile.

“I had the pleasure of working with and supporting Charlie and Paul as students. Both were highly engaged and did outstanding work,” said Phil Miller, now Assistant Dean at the Carlson School. “Their class really struggled with the depths of the financial crisis, but I suspect that helped them both in the long term. Paul was a motivated student, and we were able to connect him to a business development role post-graduation. Charlie was a driven founder from the beginning, passing up a traditional internship to work on the code base and business model for what became his first startup. Both of those journeys seem to have given them valuable experience on how they wanted their partnership in Sezzle to go. It’s been a joy to see them struggle through early challenges to the success they’re currently seeing.”

Youakim, a University of Minnesota engineering graduate and former software engineer, moved to Charlotte, North Carolina after business school and cofounded a parking technology startup called Passport. The company raised serious venture capital and grew quickly, but eventually Youakim and his cousin – his cofounder – had a falling out. He returned to Minnesota at the end of 2015 looking for a fresh start.

“He had a big chip on his shoulder,” Paradis said. “He wanted to show that he had something more in him.” Paradis, meanwhile, was growing restless in the consulting world. When Youakim called with the idea of building something new together, the timing was perfect.

The First Idea Failed Fast
The original version of Sezzle looked nothing like the company consumers know today. The founders initially believed they could reinvent ACH bank payments by authenticating bank accounts instantly, allowing merchants to avoid expensive credit card fees while still offering consumers cash-back rewards.

The concept attracted investors quickly. Thanks largely to Youakim’s reputation from Passport, Sezzle raised roughly $1.8 million in seed funding before launching its product – an unusually large pre-launch round for a Minnesota startup at the time. Investors included local angels, former Passport backers, a Belgian VC firm, and even a Chinese seed-stage investor.

But once the product launched in early 2017, the founders quickly realized they had a problem. “The small merchants didn’t care about saving 150 basis points on processing,” Paradis said. “They cared about growing their business. That’s number one, two, three, four, five.”

Consumer adoption was even worse. Even offering unsustainable cash-back incentives of 5% or 10% barely moved usage rates. After only two months in market, Youakim concluded the model was not working.

“He’s very good at that,” Paradis said of his cofounder’s willingness to take quick, decisive action. “In this case, it was a pivot, but more broadly, Charlie diagnoses a problem and immediately sets out to fix it. The rest of us were saying, ‘We raised all this money on this idea. It’s only been two months.’”

At the same time, Sezzle was pursuing a spot in the Techstars Target accelerator program in Minneapolis. The company reached the final interview stage – right as the team was internally debating whether to abandon its original business model. “We were literally debating whether to pitch the old idea or the new idea,” Paradis said.

They did not get selected. In hindsight, it may have been one of the best things that ever happened to the company.

Discovering Buy Now, Pay Later
As Sezzle searched for a new direction, Youakim noticed something interesting happening overseas. A fast-growing Australian startup called Afterpay was exploding in popularity with younger consumers. At the time, the “buy now, pay later” (BNPL) category barely existed in the United States. Another company, Affirm, focused only on large purchases like furniture and fitness equipment. But Afterpay had found something different: smaller installment payments that appealed to younger consumers wary of traditional credit cards.

Paradis and Youakim realized the U.S. market shared many of the same demographic trends as Australia, especially after the CARD Act of 2009 made it harder for young adults to get credit cards.

“We saw a bunch of Australian merchants promoting the hell out of Afterpay,” Paradis recalled. “And Charlie said Australia has always been a great test market for new tech because consumers behave very similarly to the U.S.”

The founders also discovered something critically important from regulators: if they structured the product as four payments or fewer, they could avoid many traditional lending regulations. “That’s when we said, okay,” Paradis said.

Their first sales strategy was surprisingly simple. “We started contacting all of Afterpay’s merchant customers that also sold in the U.S.,” Paradis said. “We basically pitched ourselves as ‘the Afterpay for the U.S.’”

It worked almost immediately. Merchant signups surged. And then Afterpay itself came calling.

“You Can Join Us or Compete Against Us”
Afterpay invited the Sezzle founders to San Francisco with a blunt proposition. “You can either join us or compete against us,” Paradis recalled. The Australian company offered what Paradis described as a lowball acquisition offer. Sezzle declined.

Within months, Afterpay officially entered the U.S. market with major retailers including Urban Outfitters and Revolve. Suddenly, Sezzle found itself in a brutal competitive battle against much larger, better-funded rivals.

The timing could hardly have been worse. Sezzle’s Series A financing nearly collapsed when a Chicago VC pulled its term sheet after Afterpay announced its U.S. expansion.

“That was a big blow,” Paradis said. The company needed a Plan B. Youakim provided it personally. He still owned a significant stake in Passport, his previous startup. When Passport investors offered to buy his shares during a new financing round, he sold all of his ownership and poured most of the proceeds into Sezzle. “He led the Series A himself,” Paradis said.

That decision would later become enormously important. Today, Youakim still owns a substantial portion of Sezzle, thanks partly to that personal investment during the company’s most vulnerable period.

Why Stay in Minnesota?
As Sezzle gained traction, the founders encountered another challenge familiar to many Midwest startups: coastal investors questioning why the company was based in Minneapolis.

“We’d go out to New York or San Francisco, and they’d all ask, ‘Why are you in Minneapolis?’” Paradis said. Some investors openly encouraged the company to relocate. Fundraising, especially for a fintech lender, proved much harder from Minnesota than it would have been in Silicon Valley or New York.

But Paradis says staying in Minnesota ultimately became one of Sezzle’s defining characteristics. “We were one of the only hot tech startups in town,” he said. “So if you wanted to work for a company like that, we had the buzz.”

The company recruited heavily from the University of Minnesota and Macalester College. Paradis also credits Youakim personally for choosing not to relocate the company.

“I have to give a lot of love to Charlie for that,” Paradis said. “I think he would have moved us, and he didn’t, primarily because of me. My family was here. Of course, his family was here, too, but he didn’t have kids yet. My second daughter was born the week I joined Sezzle full-time, and my wife worked for 3M. So I was much more tied down here than he was.”

The Australia Gamble
Despite improving traction, Sezzle still struggled to raise a strong Series B round in the U.S. Then an unexpected opportunity appeared. An Australian equity analyst visiting Minneapolis asked a simple question: Why not go public in Australia instead? That was a way to raise significant funds.

Australian investors already understood buy now, pay later because of Afterpay’s success. Better yet, Australia’s venture capital ecosystem was far less developed, making public listings more common for emerging tech companies. It was clearly an intriguing idea.

Youakim flew to Australia for a non-deal roadshow arranged by investment bank Ord Minnett. “He called me and said, ‘Paul, we’re doing it,’” Paradis recalled. “We were going to be able to raise a lot more money and at a much better valuation.”

The IPO process became a whirlwind. Paradis joined Youakim and Sezzle’s CFO for investor meetings across Sydney, Melbourne, and Hong Kong. At one point, after flying overnight to Hong Kong, the team showered in the airport before heading directly into all-day investor meetings in 100-degree heat and humidity. “It was incredible,” Paradis said. “We were actually planning to take a helicopter to Macau that night to celebrate, but Charlie fell asleep at the dinner table after we ate Peking Duck at the Mandarin Oriental. Still, it was a great ending to a great day.”

The company successfully listed on the Australian Securities Exchange (ASX) in July 2019.

The Crash
For a time, everything seemed to be working. Sezzle raised additional capital. The buy now, pay later market exploded globally. Affirm went public in the U.S., and markets soared during the pandemic-era fintech boom.

Then the cycle reversed – violently. Afterpay sold to Block for $39 billion in 2021, briefly fueling optimism that Sezzle might also achieve a major acquisition or Nasdaq listing. But by late 2021, fintech markets were collapsing.

Sezzle pursued both an IPO and acquisition discussions simultaneously. Nearly every potential acquirer backed away as markets cratered. Except one: Zip, a BNPL company based in Sydney.

The two companies publicly announced a merger. At the same time, Sezzle itself was under severe pressure. The company cut international expansion plans, terminated merchant partnerships, and laid off roughly a quarter of its staff. Its market capitalization collapsed from roughly $1.5 billion to just $40 million.

Nonetheless, Sezzle chose not to close the Zip deal. However, it produced a crucial lifeline: an $8 million breakup fee. Sezzle used that money to stabilize operations and race toward profitability instead of raising additional capital in a terrible market.

“We just slowly started digging ourselves out of the hole,” Paradis said.

Reinventing the Company Again
Sezzle’s eventual recovery required another strategic pivot. The merchant business had become hypercompetitive. Instead of relying solely on merchant integrations, the company shifted toward direct consumer relationships. Sezzle decided to focus on the subprime segment of the consumer market.

It launched subscription offerings, expanded its mobile app, and introduced products like Sezzle Anywhere and On Demand. The company also rebuilt carefully and efficiently.

Today, Sezzle employs roughly 500 people globally, including about 100 in the Twin Cities and approximately 250 in South America, particularly Bogotá, Colombia.

“We’ve found incredible talent there,” Paradis said. “Same time zone, highly educated, strong English skills – and much more efficient from a cost standpoint.”

Sezzle remains headquartered in downtown Minneapolis in the historic Dayton’s building, though like many tech companies it now operates largely remotely.

And despite Youakim now spending much of his time in Puerto Rico, a strategic location between Minneapolis and Bogotá, Paradis says Minnesota still matters deeply to the company’s identity. “He’s here every other week,” Paradis said. “His family’s here. Our roots are here.”

The company listed on the Nasdaq (Symbol: SEZL) in August 2023. It voluntarily delisted from the ASX, and its final day of trading on the Australian exchange was January 12, 2024.

Today, with Sezzle once again thriving, the company stands as one of the most remarkable startup success stories ever produced by Minnesota’s technology ecosystem – a decade-long journey shaped by pivots, near-collapse moments, international gambles, and an unusually stubborn commitment to building a major fintech company far from Silicon Valley.

A Strategy Well Executed
“Charlie and Paul’s ability to execute was very clear from the first time we met with them in January 2018,” said Rob Weber of Great North Ventures. “What was unclear in our initial meetings was how they were going to be able to compete against larger, more well-funded rivals Affirm, Afterpay, and Klarna. But their ability to adapt their strategy over time has been super impressive to watch.” He noted that it was Sezzle’s proprietary business intelligence system that enabled them to accomplish “far more with far less” than their rivals. “We benefited from that approach with our own startup, NativeX, before we became VCs. So we know what a difference it can make.”

Buy now, pay later (BNPL) in its earliest forms took roots through embedded partnerships across a wide range of merchant checkout processes. “It started off as a niche play, but is now emerging as core financial infrastructure,” said Weber, which he wrote about recently.

Recent Stellar Results
Sezzle reported a very strong Q1 2026 with 29.2% revenue growth, gross margins of 74%, net income of $51.3M, and adjusted EBITDA of $71.1M. Management raised full-year guidance, with revenue growth now expected to be 30%–35%, adjusted net income to $180M, and adjusted EPS to $5.10. Key drivers included improving credit performance, higher consumer engagement, and subscriber growth up 44k to 714k.

The company said product expansion is underway, including Pay-in-5, a virtual card in Canada, enhanced long-term lending, Sezzle Mobile on AT&T, and roadmap items such as deposit accounts and checking, positioning Sezzle to become an all-in-one services platform for value-focused consumers.

The company is embedding AI across support, product, and operations to increase efficiency and scale. And it is pursuing a bank charter, with an application targeted for this year, to improve regulatory defensibility and long-term economics.

“It’s going to be an exciting year for Sezzle,” said CEO Charlie Youakim on the earnings call. “2025 was about enhancing our current consumer ecosystem. We improved the app experience, expanded engagement features, leaned back into higher-value consumers, and continue to give our users more reasons to come back to Sezzle. But in 2026, we’re pushing that strategy further. We’re moving beyond being a product consumers think about only at checkout.”

He sums it up this way: “We’re building an all-in-one services platform for the value-focused consumer. The strategic goal is to make Sezzle more useful in more moments. The more value we provide, the more reasons consumers have to come back… We should see consumers using Sezzle more often across more merchants and across more use cases. That’s exactly what we saw in the first quarter.”

As the month of May 2026 came to an end, investment site Seeking Alpha named Sezzle the best performing financial stock of the month based on one month price performance percentage. In addition, that same week, another site published this article: Sezzle Tops the List of Best All-in-One Fintech Apps of 2026.

Learn more about this amazing fintech success story at Sezzle.com.


The Day Minnesota Became a Fintech Startup Hotbed

There was definitely some tension in the air, as six startups were about to pitch on stage. One of them had never even pitched in public before. Little did three of them know what this day would come to mean, and how their lives would change over the ensuing years.

Illustration depicting fintech applications around a banner saying "MN Fintech Pioneers"

The scene was an auditorium at the University of Minnesota’s Carlson Business School, at a “Financial & Retail Analytics” conference we called FARCON. It was almost ten years ago – August 2016, to be exact. I was hosting the pitch session. This little-remembered Startup Showcase, as we called it, quietly captured a pattern that would come to define Minnesota’s role in fintech and commerce innovation.

On that stage pitching were Sezzle, GrocerKey, and LiveGiveSave. A year later, at FARCON  2017 at the U’s McNamara Alumni Center, a Techstars cohort startup named Branch Messenger would pitch as well.

None of these companies was framed as “fintech” at the time. They were analytics companies. Retail companies. Behavior companies. But in hindsight, they were all working on the same underlying problem: how money moves through everyday consumer and workforce interactions.

Sezzle went on to pivot to buy now, pay later (BNPL). It did not invent it, but localized and operationalized it for a specific segment, aligning tightly with U.S. retail behavior and merchant needs. Branch, then a workforce communications platform, sat directly on top of shift work, payroll, shift cycles, and employee engagement – precisely the layer that would later enable earned wage access. LiveGiveSave, later rebranded as Spave, connected spending to saving and giving, anticipating today’s wave of embedded and values-driven financial tools. And GrocerKey built the infrastructure for local grocery e-commerce, an early signal of the digitization of everyday retail.

What ties these companies together is not category creation, but context. Each emerged from Minnesota’s unique intersection of large-scale retail, enterprise systems, and applied analytics. They didn’t start by trying to disrupt finance. They started by solving practical problems in online life and commerce – then extended into financial layers.

The outcomes were equally telling. Sezzle scaled into a publicly traded company, now with a whopping market capitalization of more than $2B (Nasdaq: SEZL). Branch evolved into a leading earned-wage access platform, growing rapidly and now partnered with Stripe. GrocerKey (which was based in Madison WI with Minnesota operations) exited to a strategic buyer, a success for the founding team. And Spave followed a less conventional path: a meaningful exit followed by the founder buying back the name and rights to certain markets to continue building the platform and operating the company independently.

Together, as we look back today, it’s quite clear these four companies can stand proudly as early Minnesota fintech pioneers. Big kudos to them!

We can be sure, however, that much more fintech innovation is yet to come in our state. Stay tuned!

« Older posts